In an ENERGDIVE interview, former Power Secretary Pradeep Kumar Pujari explains how decarbonisation, market reform and grid modernisation are driving decentralised, data-led, consumer-centric power markets shaping India’s electric future.
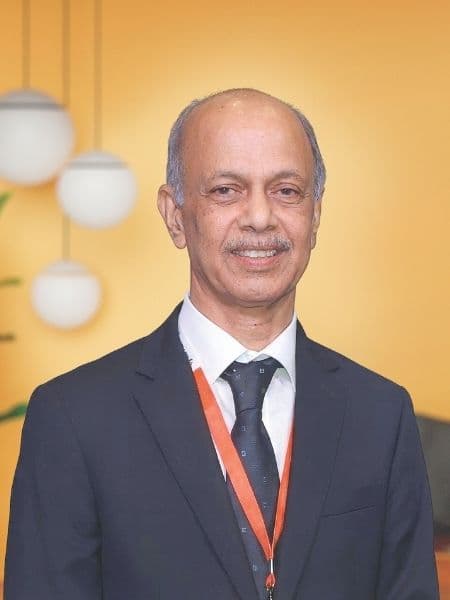
India’s energy transition is entering its most decisive phase yet, where decarbonisation, market reform and grid modernisation must advance together. In an interview with ENERGDIVE, former Power Secretary and ex-Central Electricity Regulatory Commission (CERC) Chairperson Pradeep Kumar Pujari lays out the structural shifts redefining the sector: from decentralised generation and real-time markets to the coming “UPI moment” in power. His insights point to an ecosystem moving toward data-driven governance, flexible system design and consumer-centric markets, the pillars on which India’s electric future will be built.
The disruptive technologies have necessitated the transformation of the structure of power sector governance the most in the last decade. Traditionally, there used to be a large generation, transmission and distribution. With renewables coming in, the generation has become largely decentralised and in many cases, consumers have become prosumers. At the same time, extensive digitalisation has given opportunity to every player the opportunity to actively participate in the power market by responding to the price signals.
Several transformative measures have been taken to put in place the required policy and regulatory ecosystem to address the challenges due to large-scale integration of renewable energy and facilitate the same and digitalisation. New markets and market products have been introduced. As the grid operation has become more complex, resource adequacy, flexible resources and RTC Power & FDRE have become key.
This was possible because policy and regulation began to work in tandem – policy set the direction, such as universal access, renewable push and distribution reforms, while regulation ensured predictability, enforcement and fair price discovery. The governance became data-driven. The objective is to institutionalise this alignment.
SCED has delivered lower variable-cost dispatch, resulting in better utilisation of thermal capacity. The RTM has given stakeholders the much-needed platform for balancing resources, resulting in improved grid discipline. At the same time, these have also resulted in more liquidity in the market. Going forward, co-optimisation could be an option for higher efficiency.
The trilemma of reliability, affordability and decarbonisation is a real challenge. The policy and regulatory measures are aimed at striking the right balance. India’s electricity portfolio will run a dual-track system for some time: rapid growth in non-fossil capacity with emphasis on FDRE and RTCRE, alongside flexible and efficient thermal for ramping and adequacy.
The priority is to encourage investment in pumped hydro, storage and flexible gas where viable, operational flexibility of the existing fleet, and resource adequacy. Rapid addition of renewable, preferably FDRE and RTC, retail tariffs reforms and targeted subsidies can deliver reliable and affordable electricity without compromising the decarbonisation objective.
Sustainable DISCOMs require structural fixes, not episodic bailouts. Financial viability is the single biggest unlock for the entire value chain. I would recommend these actions on priority: AT&C loss reduction anchored in smart metering, feeder segregation and energy accounting; cost-reflective tariffs, timely true-ups and regulatory assets only in exceptional circumstances, that too with a clear roadmap for liquidation; tariff rationalisation, including Time-of-day tariffs & DBT of subsidies to insulate the vulnerable consumers, exploring PPP models for DISCOM operations, and capacity building.
The IES is conceived as DPI for the power sector. It will be open, secure and interoperable, so that utilities, regulators, market operators and consumers can share consented data, transact seamlessly, and innovate at the edge. IES can be seen as a ‘UPI Moment’ for the electricity sector: open APIs, unique identifiers for assets and transactions, and policy-grade data semantics enabling everything from automated settlements to consumer centric services and real-time system intelligence. The focus of the Task Force is on proving value through pilots, creating the ecosystem for scale, and ensuring that innovations flourish without fragmenting the core.
Regulation should be principle-based and technology agnostic. For storage, clarity as to whether it is a separable asset class is important. For pumped hydro, long tenor contracting and site-specific incentives matter. For distributed resources, enabling aggregation and participation in markets with light-touch consumer protection is the key. For green hydrogen, initial regulation can focus on safety, interconnection standards and fair network access. Regulatory sandboxes can accelerate learning, which can facilitate framing appropriate policies and regulations.
Tariff design must evolve with the energy mix. As the renewable and storage scale increases, flat volumetric tariffs may not be the best option. Possible solutions could be Time of Day Tariff, Real-time Pricing for large segments, Capacity/Demand Charges that reflect the network costs, and Cost-Reflective Wheeling Charges for open access consumers. These have to be combined with DBT-backed tariff slabs to protect vulnerable lifeline households.
There is also a need to explore the possibility of moving towards a two-part retail tariff construct, a predictable subscription/network component and a dynamic energy component. Such an arrangement would tend to align the consumer behaviour with system needs, without impacting affordability.
A South Asian power pool is in India’s strategic interest. The building blocks are harmonised grid codes, transparent scheduling and settlements, bankable cross-border interconnections, and open access to markets for credible counterparties. With common market platforms and firm financial transmission rights, there can be a move from bilateral trade to a regional market, leveraging and monetising the diversity of resources across the subcontinent.
Independent institutions with the required capability are important. There is a need for stronger analytics capacity across such institutions, with shared data backbones. In this background, coordination amongst such institutions becomes crucial. There is a need for an institutionalised secretariat and an inter-state coordination forum. There is also a need to put in place time-bound regulatory processes with measurable outcomes and carry out regulatory impact assessments for major changes. Regulatory certainty, predictability and consistency are essential for investors’ confidence.
In my view, the three key markers would be: efficient distribution utilities with strong financial health, system adequacy with flexibility and strong consumer interface enabled by IES, and a deepened market with real-time, intra day, day-ahead, term-ahead and ancillary products.